
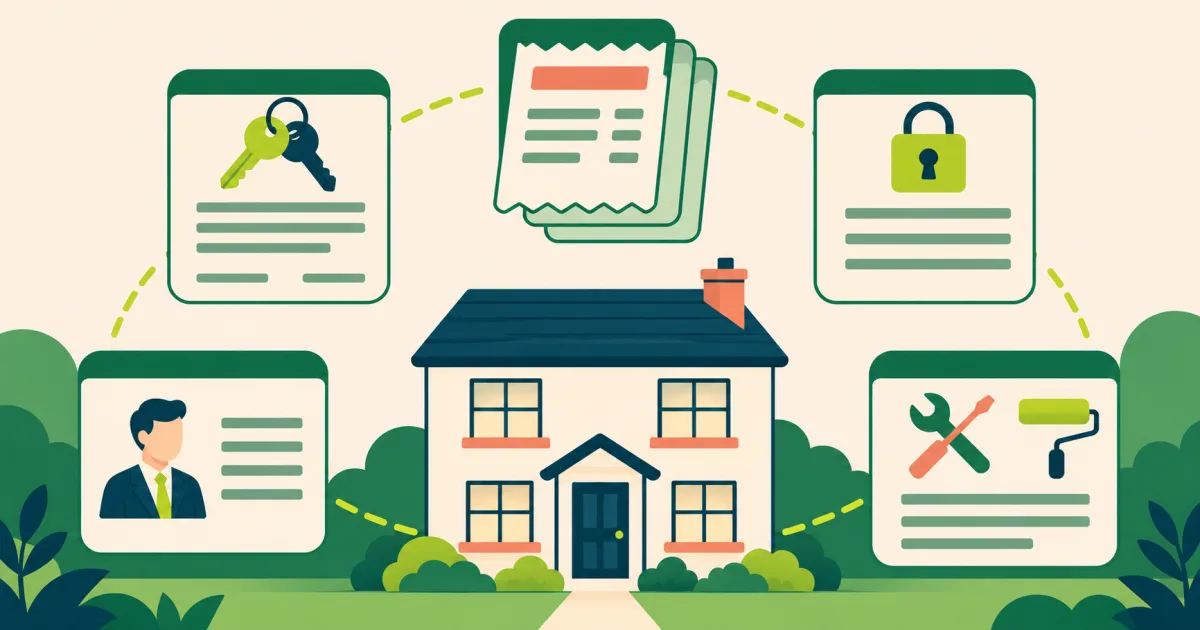
Rental cash should be separated from deposits, owner transfers and reimbursements before tax treatment is considered. A property ledger connects the tenancy agreement, expected rent, actual receipts, arrears and expenses to one property and period. It prevents a bank account from becoming the only explanation of the activity.
Separate deposits from rent
A security or utility deposit may be refundable and should not be silently counted as ordinary rent. Record its purpose, holder and later return or application. The legal and tax treatment depends on the facts.
Build one ledger per property
Record tenant, agreement dates, monthly rent, due dates, receipts, arrears and adjustments. Keep each property separate even when rent enters one bank account. Link renewals and rent changes to written agreements.
- Tenancy agreement: Rent, dates and deposit terms
- Receipt ledger: Expected and actual payments
- Agent statement: Gross collection and fees
- Expense evidence: Property and business purpose
Tenancy agreement
Rent, dates and deposit terms. For Rental Income Records, use the tenancy agreement beside the receipt ledger to test separate deposits from rent. Keep its source, period and status visible when completing prepare a property-year summary.
Receipt ledger
Expected and actual payments. For Rental Income Records, use the receipt ledger beside the agent statement to test separate deposits from rent. Keep its source, period and status visible when completing prepare a property-year summary.
Agent statement
Gross collection and fees. For Rental Income Records, use the agent statement beside the expense evidence to test separate deposits from rent. Keep its source, period and status visible when completing prepare a property-year summary.
Expense evidence
Property and business purpose. For Rental Income Records, use the expense evidence beside the tenancy agreement to test separate deposits from rent. Keep its source, period and status visible when completing prepare a property-year summary.
Classify costs carefully
Keep invoices, payment proof and the reason each cost relates to the property. Capital improvements, repairs, financing and personal costs can have different treatment. Do not classify solely by the merchant name.
Agent statement example
If an agent collects $2,000 rent, deducts $160 fees and transfers $1,840, record the gross receipt and fee separately. Reconcile the agent statement to the bank rather than treating the deposit as the entire transaction.
Prepare a property-year summary
For each year, summarise gross rent, vacancies, arrears, refunds, fees and supported costs. Reconcile deposits and keep the filed result with the source ledger. Seek qualified advice for classification questions that materially change the return.
Keep each property separate
In the Rental Income Records review, keep each property separate uses the agent statement to verify gross collection and fees. Resolve the point against classify costs carefully and record the dated outcome.
Track refundable deposits
In the Rental Income Records review, track refundable deposits uses the expense evidence to verify property and business purpose. Resolve the point against classify costs carefully and record the dated outcome.
Record gross before fees
In the Rental Income Records review, record gross before fees uses the tenancy agreement to verify rent, dates and deposit terms. Resolve the point against classify costs carefully and record the dated outcome.
Document cost purpose
In the Rental Income Records review, document cost purpose uses the receipt ledger to verify expected and actual payments. Resolve the point against classify costs carefully and record the dated outcome.
Where Rental Income Records fits in the income record
Rental records join other income sources only after the property ledger has been reconciled. Continue the multiple income review through these exact calculation and record pages: multiple-income planner multiple-income guide annual documents checklist.
Final evidence check for Rental Income Records
For Rental Income Records, the closing file connects tenancy agreement, receipt ledger, agent statement, expense evidence. Complete Prepare a property-year summary only after Separate deposits from rent explains the result and Classify costs carefully records what remains uncertain. Keep the dated working result separate from any later employer, agency or tax-authority figure.
Source boundary for Rental Income Records
For Rental Income Records, OECD Taxing Wages 2026 anchors the general concept rather than a local result. The relevant tax authority controls the tax treatment of rental activity. This article does not determine whether a particular cost is deductible. Apply the FROM.MY verification method to the facts identified under classify costs carefully before acting.