
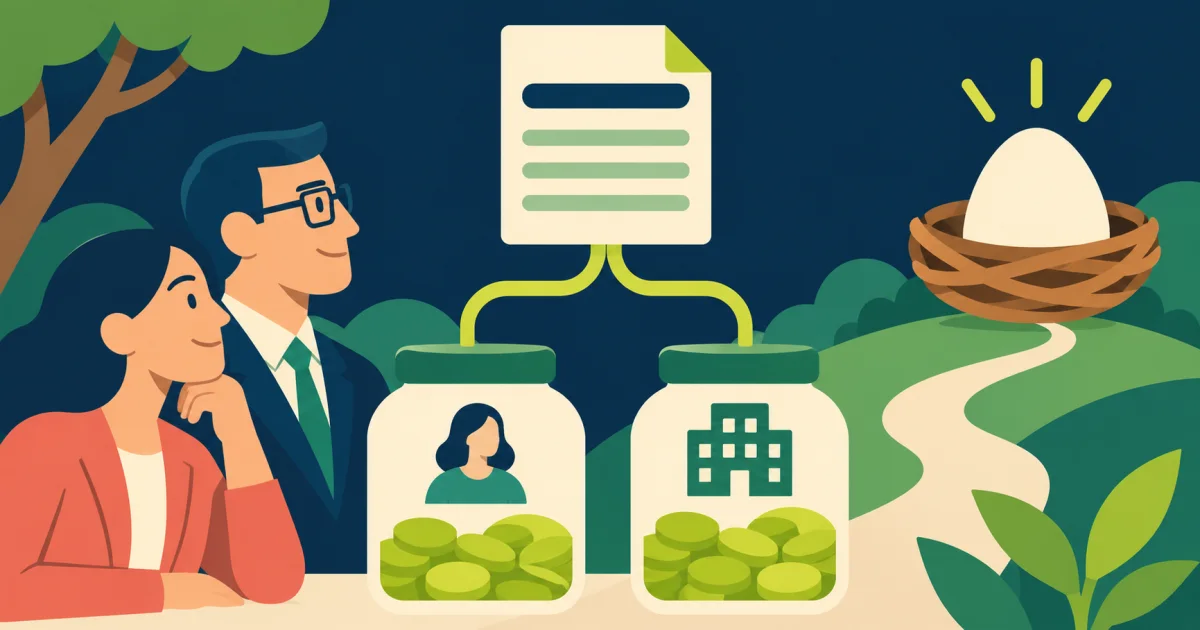
Separate the employee and employer amounts
An employee contribution normally comes out of gross pay. An employer-funded contribution is additional compensation paid to the plan. Keep both lines visible, but subtract only the employee amount when estimating take-home pay.
Identify the rule behind the contribution
Plans can use a percentage of eligible pay, a fixed amount, a matching formula or a tiered schedule. Confirm which earnings count, whether a contribution ceiling applies and whether bonus, overtime or allowances are included. Use the plan document and a recent statement rather than assuming the headline rate applies to every pay line.
| Question | Record to check | Why it matters |
|---|---|---|
| What reduces take-home pay? | Payslip employee contribution | This is the cash deduction |
| What does the employer add? | Employer plan statement | This belongs in total compensation |
| Is there a cap or threshold? | Current plan rules | The percentage may stop or change |
| When is the money yours? | Vesting schedule | Unvested value may be lost after leaving |
Use contributions in two different decisions
For a monthly budget, focus on the employee deduction and resulting net pay. For a job-offer comparison, add employer-funded value and check vesting, fees and investment access. A larger employer contribution can improve an offer without helping this month's rent.
Reconcile the actual record
Match the contribution on the payslip to the amount credited to the retirement account for the same pay period. If the figures differ, first check eligible earnings, rounding, timing and corrections from an earlier period. Ask payroll one focused question that names the period and disputed line.
Choose the retirement plan schedule before checking the amount
A useful retirement plan review starts with employee facts, not a percentage. Record the wage month, age band, citizenship or permanent-resident status, registration history where relevant, and the wages payroll treated as contributable. These facts identify the schedule and category. Only then should the payslip amount be compared with the official row.
Suppose two offers both state $5,500 monthly salary. An offer comparison that subtracts employee retirement contribution from one offer but ignores employer-funded retirement contribution on the other mixes cash flow with total compensation. Show four separate figures: contractual gross cash, estimated employee contribution, estimated take-home pay, and employer contribution. The employee share affects money available now. The employer share adds retirement value but cannot be spent as salary.
When a percentage estimate and payslip differ
Do not immediately label a small difference an error. For wages covered by contribution tables, payroll may use the statutory wage band and scheduled amount instead of a raw multiplication. Compare the exact contributable wage and row. If an allowance is included by payroll, ask why it is treated as wages. If it is excluded, keep the policy or explanation supporting that treatment.
When the member statement is the final missing record
A correct payslip deduction does not by itself prove that both shares reached the member account. Match the wage month, employer, employee share and employer share to the statement after the normal posting period. Record any correction as a new event instead of overwriting your original worksheet. That creates a clear trail for payroll, retirement plan or a later job transition.
Compare two retirement packages without overstating value
Begin with guaranteed cash salary, then add the employer contribution expected during the same twelve-month period. Do not add the employee contribution as extra compensation because it comes from the employee's own gross pay. If one plan requires an employee contribution to unlock an employer match, show the required cash deduction and unlocked employer value on separate rows.
Next, test vesting. An employer may credit a contribution today while ownership becomes permanent only after a service period. For a person likely to leave before vesting, expected value can be lower than the headline contribution. Use a downside case with only vested value, a base case using the expected leaving date and an upside case for full vesting. Do not assign a probability unless the worker has a reason for it.
Account for fees and access
Contribution size is not the whole benefit. Record administrative fees, investment costs, withdrawal restrictions, transfer options and any employer stock concentration. These facts do not turn retirement value into current cash, but they can change the value of two otherwise similar employer contributions.
Keep a contribution ledger
For each pay period, record eligible earnings, employee deduction, employer-funded amount, payroll date and account posting date. Mark corrections as new entries rather than overwriting the original row. This makes delayed posting visible and preserves the evidence needed for a payroll question.
Questions to ask before relying on the figure
- Which earnings are eligible for employee and employer contributions?
- Does the plan use a match, fixed employer rate or discretionary amount?
- Is there an annual ceiling, waiting period or minimum service rule?
- When does employer-funded value vest?
- Where can the contribution be verified after payroll?
A calculator can model the cash effect once these answers are known. It cannot decide plan eligibility, tax treatment or ownership from salary alone. Use the plan document, payslip and account statement as three separate records, then escalate a mismatch with the exact pay period and amount.
Use one comparison date
Value both offers or payroll periods on the same date so vesting, posting delays and contribution changes do not distort the comparison.