
Classify annual income
Bring employment, bonus and other relevant sources into the correct annual computation.
Build the annual calculation in layers: identify taxable income, subtract supported deductions and personal reliefs, apply progressive resident rates, then consider rebates and tax already paid. payroll tax withholding is part of the reconciliation, not a separate final tax.
Use the resident tax brackets for the rate layers, the relief and rebate comparison for adjustments, and the payroll tax withholding guide for payroll reconciliation. Readers with freelance, rental or business receipts should continue with the multiple-income records and tax pathway.
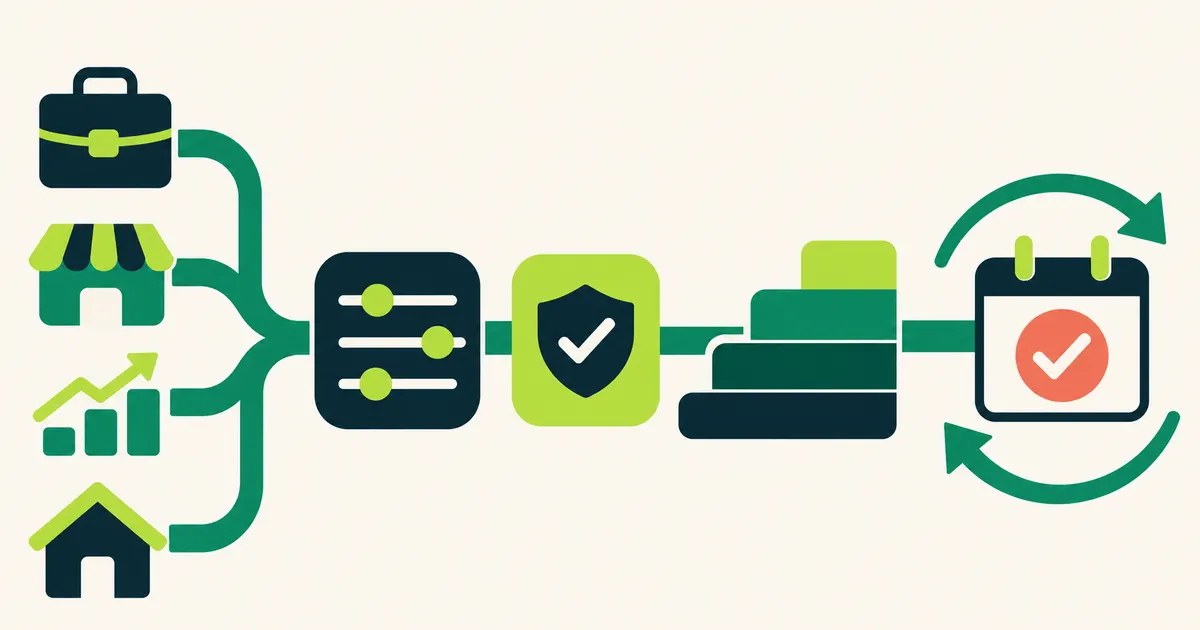
Connect taxable income, planning rates, payroll withholding, other payments and the estimated final balance without assuming one tax system.
Bring employment, bonus and other relevant sources into the correct annual computation.
Separate deductions, reliefs and rebates and retain evidence for each claimed category.
Compare scheduled tax with payroll tax withholding and other tax already paid before estimating a balance or refund.
If a payroll or tax term is unfamiliar, check the salary and income glossary before applying it to a calculation.
Gross receipts, taxable income, allowable deductions, personal reliefs, progressive rates, rebates and tax already paid are different layers. The guides in this hub keep those layers visible so one receipt or payroll deduction is not counted twice.
payroll tax withholding is collected through payroll using prescribed information and methods. The final annual position can change because of bonus, another employer, side income, relief evidence and rebates. Track both year-to-date payroll tax withholding and a full-year estimate.
The tools provide transparent planning estimates. Final liability depends on complete facts and current the relevant tax authority rules. Keep the evidence, calculation version and official source date beside every material estimate.
No. A progressive rate applies only to the chargeable-income slice inside that band.
Not always. The annual return can reconcile other income, reliefs, rebates and tax already paid using the taxpayer's full-year facts.
No. A relief reduces chargeable income, while a rebate reduces tax after the rate calculation, subject to its rules.
Payroll withholding is a prepayment or collection mechanism. Final tax can change after annual income, deductions, credits, filing status and tax already paid are reconciled.
Reviewed 2 November 2026In a progressive system, the highest rate reached normally applies only to income inside that band. The effective rate measures total tax divided by the chosen income base.
Reviewed 2 November 2026A deduction generally reduces the income subject to tax. A credit or rebate generally reduces calculated tax. Eligibility, limits and refundability depend on the applicable tax rules.
Reviewed 2 November 2026Collect records by income source and claim category, then reconcile them to bank and payroll totals before starting the return.
Reviewed 2 November 2026A bonus can affect retirement plan and payroll tax withholding, and the tax effect depends on annual income rather than a universal bonus-tax rate. Estimate it by comparing full-year tax with and without the bonus.
Reviewed 2 November 2026Reserve tax from net side-income cash using a documented planning rate, then reconcile the reserve to a full-year tax estimate as income and allowable costs become clearer.
Reviewed 2 November 2026Estimate annual tax using the effective rate that fits your jurisdiction and circumstances. Confirm material figures against payroll and official records.