
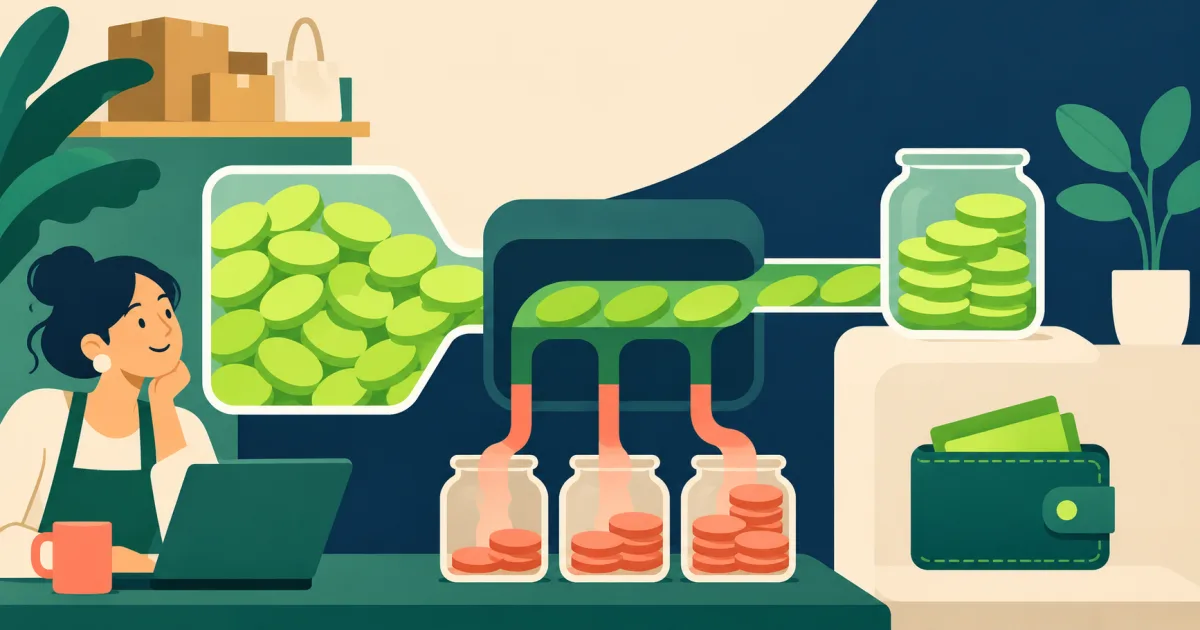
Revenue is what the activity earns before costs. Profit is what remains after supported business costs under the chosen accounting and tax treatment. Owner cash is what is transferred to the household. Treating all three as the same number can overstate income and underfund tax or operations.
Separate business costs
Record fees, materials, delivery, software and other costs with evidence and business purpose. Tax deductibility is a separate official question; the operating view should still show what the activity consumed.
Create a monthly bridge
Bridge opening cash, gross receipts, refunds, fees, operating payments, owner transfers and closing cash. Then prepare the profit and tax schedules from the appropriate records.
Record gross first
In the Side Hustle Profit vs Revenue review, record gross first uses the refunds and fees to verify separate transaction costs. Resolve the point against do not confuse cash and profit and record the dated outcome.
Explain every bank deposit
In the Side Hustle Profit vs Revenue review, explain every bank deposit uses the operating costs to verify supported business use. Resolve the point against do not confuse cash and profit and record the dated outcome.
Keep owner draws separate
In the Side Hustle Profit vs Revenue review, keep owner draws separate uses the owner cash to verify transfer to household, not expense. Resolve the point against do not confuse cash and profit and record the dated outcome.
Reconcile monthly
In the Side Hustle Profit vs Revenue review, reconcile monthly uses the gross revenue to verify customer value before reductions. Resolve the point against do not confuse cash and profit and record the dated outcome.
Platform-sale example
A platform shows $6,000 sales, $300 refunds and $600 fees, then transfers $5,100. The $5,100 deposit is neither gross revenue nor automatically profit because other costs may remain.
Do not confuse cash and profit
Buying inventory can reduce cash before the full accounting effect is known. An owner draw reduces business cash but is not the same as a business expense. Keep these events in distinct columns.
Record gross revenue
Capture customer payments before refunds and fees. Keep sales channels separate enough to reconcile platform statements and bank deposits. Personal transfers into the business are not sales.
| Record or input | What to verify |
|---|---|
| Gross revenue | Customer value before reductions |
| Refunds and fees | Separate transaction costs |
| Operating costs | Supported business use |
| Owner cash | Transfer to household, not expense |
Gross revenue
Customer value before reductions. For Side Hustle Profit vs Revenue, use the gross revenue beside the refunds and fees to test separate business costs. Keep its source, period and status visible when completing create a monthly bridge.
Refunds and fees
Separate transaction costs. For Side Hustle Profit vs Revenue, use the refunds and fees beside the operating costs to test separate business costs. Keep its source, period and status visible when completing create a monthly bridge.
Operating costs
Supported business use. For Side Hustle Profit vs Revenue, use the operating costs beside the owner cash to test separate business costs. Keep its source, period and status visible when completing create a monthly bridge.
Owner cash
Transfer to household, not expense. For Side Hustle Profit vs Revenue, use the owner cash beside the gross revenue to test separate business costs. Keep its source, period and status visible when completing create a monthly bridge.
Where Side Hustle Profit vs Revenue fits in the income record
This distinction improves the multiple-income plan, tax reserve and freelance rate floor. Continue the multiple income review through these exact calculation and record pages: multiple-income guide income planner tax reserve guide.
Final evidence check for Side Hustle Profit vs Revenue
For Side Hustle Profit vs Revenue, the closing file connects gross revenue, refunds and fees, operating costs, owner cash. Complete Create a monthly bridge only after Separate business costs explains the result and Do not confuse cash and profit records what remains uncertain. Keep the dated working result separate from any later employer, agency or tax-authority figure.
Source boundary for Side Hustle Profit vs Revenue
For Side Hustle Profit vs Revenue, OECD Taxing Wages 2026 anchors the general concept rather than a local result. The relevant tax authority controls the tax treatment of business receipts and costs; the bridge is a recordkeeping framework. Apply the FROM.MY verification method to the facts identified under do not confuse cash and profit before acting.